What Is the Kelly Criterion? Position Sizing for Crypto Trading
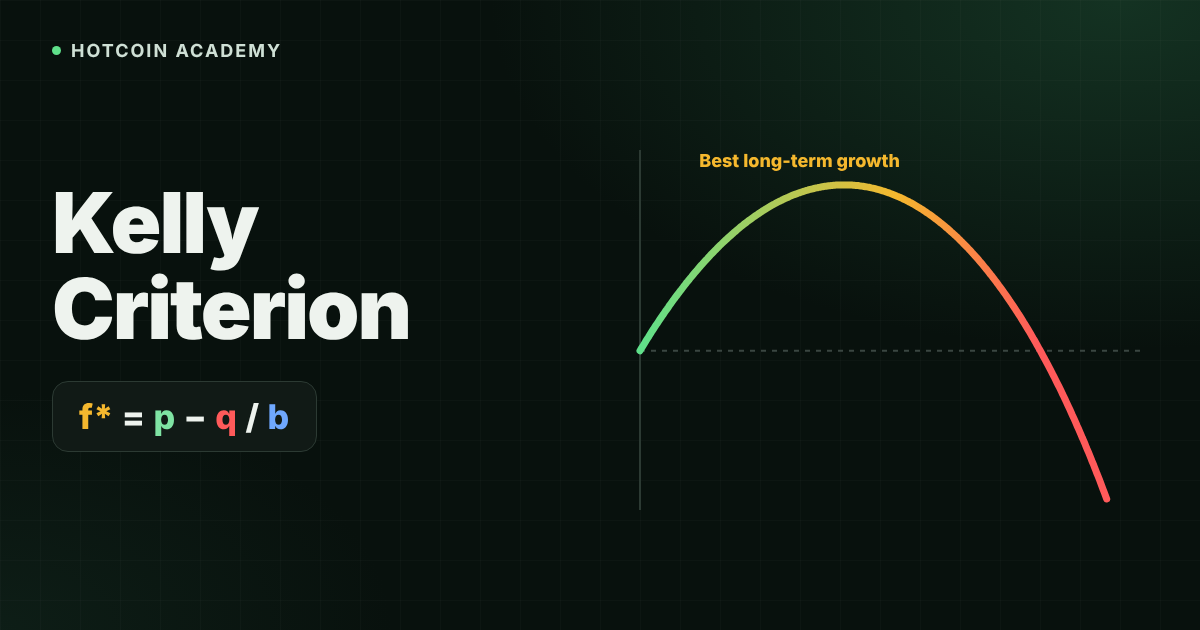
Trading is not just about "whether to buy" — it often gets stuck on "how much should I bet on this trade." The Kelly criterion is exactly designed to answer: given a known win rate and payoff ratio, what percentage of capital roughly maximizes long-term compound growth.
It optimizes long-term logarithmic wealth / geometric growth rate — not predicting the next candlestick, and it cannot guarantee profits. If you misestimate the win rate or payoff ratio, then add leverage, you may accelerate losses instead.
This article uses copyable formulas and step-by-step calculations to explain the concepts. Content is for educational purposes only and does not constitute investment advice.
Key Takeaways
- The Kelly criterion uses win rate p and payoff ratio b to give the theoretically optimal bet (position) size
f*; the common formula isf* = p − (1 − p) / b, equivalent tof* = (b × p − q) / b(whereq = 1 − p). - In crypto markets, p and b are extremely hard to estimate stably. In practice, fractional Kelly such as half Kelly or quarter Kelly is often used to reduce volatility and model error.
- When interpreting
f*as "the proportion of equity at risk", you still need to combine it with stop-loss distance to convert to notional position size; do not treat the Kelly ratio directly as contract leverage. - Kelly output ≠ guaranteed profit; full Kelly is especially dangerous when estimation errors, consecutive losses, and high leverage compound.
What Is the Kelly Criterion? Definition and Formula
The Kelly criterion was proposed by Bell Labs researcher John Larry Kelly Jr. in 1956. The core idea is to choose a bet size that maximizes long-term expected logarithmic wealth (equivalent to long-term geometric growth rate). See the public encyclopedia entry: Kelly criterion (Wikipedia).
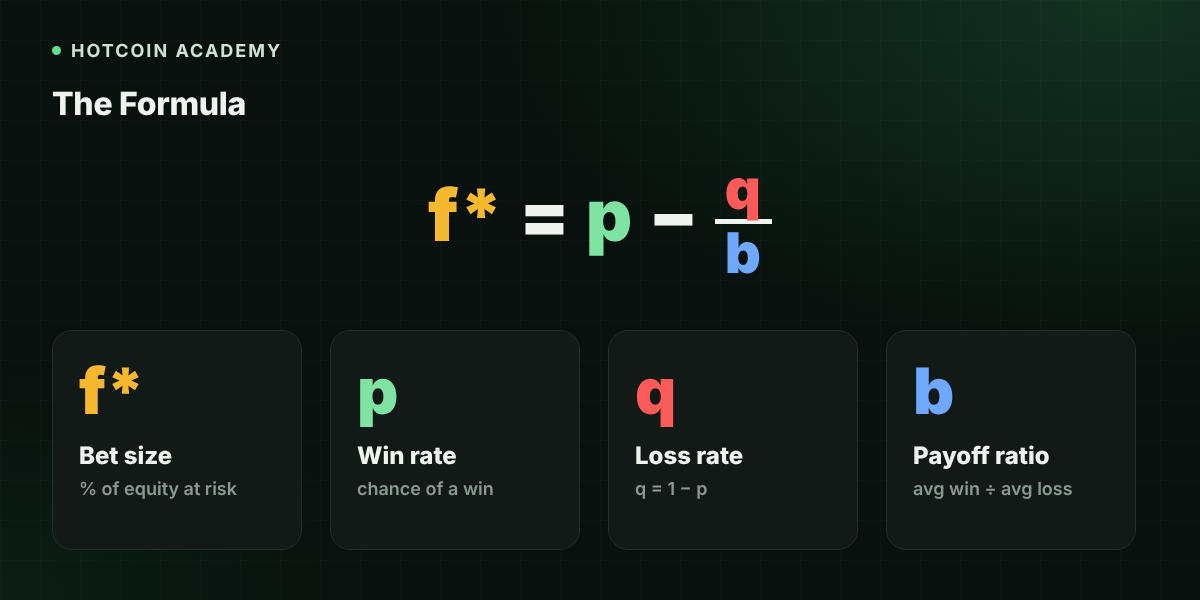
For a simplified binary win/loss scenario where a loss incurs a predetermined percentage loss, the common copyable formula is:
f* = (b × p − q) / b
Equivalent form:
f* = p − q / b
Symbol definitions:
| Symbol | Meaning |
|---|---|
f* |
Theoretically recommended proportion of capital (equity) to invest/risk |
| p | Probability of profit (win), often called win rate |
| q | Probability of loss, q = 1 − p |
| b | Net payoff ratio: average profit relative to average loss (avg win / avg loss); in gambling context, can also be understood as net win per 1 unit wagered |
If you keep a trading journal, an equivalent form is also common:
Kelly% = W − (1 − W) / R
Where W is historical win rate and R is average profit ÷ average loss. When mapped one-to-one with p and b above, the values should match.
Assumptions and Limitations: Why Crypto Makes Full Kelly Particularly Difficult
The Kelly criterion strictly holds only when outcome probabilities are known and stable; real investing almost never satisfies this. Crypto scenarios have additional friction:
- p is not constant: A win rate backtested in a bull market may fail in ranging or one-sided downtrends.
- b must use net results: Fees, slippage, and perpetual funding rates all eat into the gross profit/loss ratio.
- Correlation: Suppose you open 5 long positions. If they are all major coins plus high-beta coins, they tend to fall together when the market drops — risk-wise it's more like 1 large position; calculating Kelly for each and adding them up is equivalent to betting the same direction multiple times.
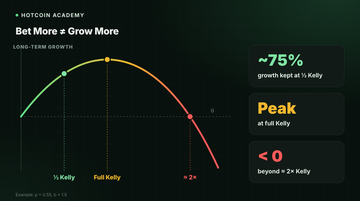
- Consecutive losses and psychology: Even with positive expectancy, the full Kelly path can experience very deep drawdowns; when bet size exceeds
f*, long-term growth rate actually declines; around roughly 2×f*(approximate, varies with p and b) it turns negative, so even with an edge you may shrink over time, and long-term bankruptcy risk rises.
Therefore, Kelly is better suited as a position cap reference after you have a statistical edge, not a magic formula that creates an edge.
How to Use Kelly for Position Sizing in Crypto Trading
First, clarify: Kelly gives a risk/allocation ratio relative to equity, not an automatic answer for how much leverage to use. To practice record-keeping and estimating p and b in a zero-risk environment, you can use Hotcoin Demo Trading.
- First confirm positive expectancy: Without a verifiable edge, a beautiful
f*only magnifies errors; whenf* ≤ 0, the strategy should be suspended. - Use a sufficient and relatively recent sample to estimate W, R (or p, b): Include net P&L after fees and slippage; avoid treating an extremely short backtest or a single market regime as permanent parameters. When trade records are too few, first use fixed-fraction risk to control positions, and refer to Kelly once the sample is sufficient.
- Calculate full Kelly
f*, then switch to fractional Kelly: Commonly start with half Kelly or quarter Kelly, and set a hard cap (e.g., single-trade risk not exceeding a fixed percentage of equity). - Use stop-loss distance to convert "risk amount" to notional position size: Risk amount ≈ equity × (fractional Kelly ratio); notional position ≈ risk amount ÷ stop-loss percentage (price percentage).
- Treat leverage as a separate risk control: Notional position, margin, liquidation price, and funding rate are another layer of constraints. Leverage amplifies P&L proportionally; see Leverage and Forced Liquidation for mechanics. Never treat
f*directly as "how many times leverage to use."
Complete Worked Example: From Win Rate and Payoff Ratio to Half Kelly Position
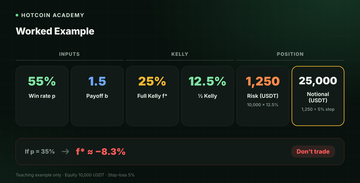
The following are teaching hypothetical numbers, not real win-rate predictions for any coin. Assume a strategy's net result estimates: win rate p = 0.55 (so q = 0.45), average profit / average loss b = 1.5. Assume account equity is 10,000 USDT, and planned stop-loss distance is 5% of price.
Step 1: Calculate full Kelly f*
f* = (1.5 × 0.55 − 0.45) / 1.5
   = (0.825 − 0.45) / 1.5
   = 0.375 / 1.5
   = 0.25
Cross-check: f* = p − q / b = 0.55 − 0.45 / 1.5 = 0.55 − 0.3 = 0.25 (25%).
Step 2: Fractional Kelly
| Method | Calculation | Ratio |
|---|---|---|
| Full Kelly | f* |
25% |
| Half Kelly | f* / 2 |
12.5% |
| Quarter Kelly | f* / 4 |
6.25% |
Step 3: Convert to "maximum loss on this trade" and notional position (using half Kelly as example)
| Item | Calculation | Result |
|---|---|---|
| Equity | Given | 10,000 USDT |
| Half Kelly risk ratio | 12.5% | — |
| Maximum acceptable loss per trade (risk amount) | 10,000 × 12.5% |
1,250 USDT |
| Stop-loss distance | Given | 5% |
| Corresponding notional position (approx.) | 1,250 ÷ 5% |
25,000 USDT |
Interpretation: Half Kelly here represents the notional size reference when "if stop-loss triggers, loss is about 12.5% of equity"; if using quarter Kelly, the risk amount and notional position are roughly halved. Actual orders are also subject to liquidity, margin, and liquidation constraints.
Note that a notional position of 25,000 USDT is already 2.5× equity — spot-only trading cannot buy this size; with contracts, margin is approximately notional position ÷ leverage. Leverage only changes margin, not the loss amount when stop-loss triggers (provided liquidation price is not hit before stop-loss).
Additionally, a single-trade risk of 12.5% is still high for most accounts — this precisely shows that a strategy without much edge cannot support large positions.
Conversely, if win rate is only 35% with the same 1.5 payoff: f* = 0.35 − 0.65 / 1.5 ≈ 0.35 − 0.433 = −0.083, a negative result, meaning you should not bet under these conditions.
How to Choose Among Half Kelly and Other Variants?
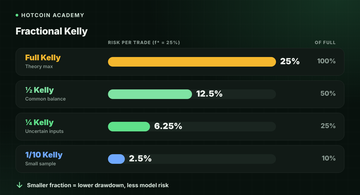
| Variant | Relative to Full Kelly | Common Use (Educational) |
|---|---|---|
| Full Kelly | 100% | Theoretical optimal growth; rarely used directly in crypto due to parameter error and drawdowns |
| Half Kelly | 50% | Common compromise: lower volatility, retain some growth |
| Quarter Kelly | 25% | More conservative; when parameters are very uncertain |
| Tenth Kelly etc. | Smaller | Conservative starting point for high volatility or insufficient sample |
In practice, bets are often below full Kelly to reduce bankruptcy probability, volatility, and model error; this is a trade-off between risk preference and estimation uncertainty, not a guarantee of higher profits.
Common Misconceptions
- Treating backtested win rate directly as real p: Overfitting and regime shifts make
f*too large. - Ignoring consecutive loss paths: Positive expectancy can still have consecutive losses; oversized positions force you to abandon the system midway.
- Insisting on full Kelly: Slightly optimistic estimates can make recommended positions significantly too high.
- Treating Kelly ratio as contract leverage:
f*governs risk as a proportion of equity; leverage also involves notional exposure and liquidation. - Treating same-direction positions as diversification: Several long positions with the same direction and highly correlated price action are risk-wise closer to one large position.
FAQ
Q1: What is the Kelly criterion? The Kelly criterion is a formula that calculates the capital allocation/risk ratio for better long-term growth given known or estimated win rate and payoff ratio. It does not predict price direction.
Q2: Can the Kelly criterion guarantee profits? No. It only optimizes long-term growth when input assumptions roughly hold; if inputs are wrong, the formula amplifies errors.
Q3: Why is half Kelly or quarter Kelly commonly used in crypto? Because win rates and payoff ratios are hard to estimate accurately, volatility is high, and there are fees and funding rates; fractional Kelly reduces the impact of volatility and model error.
Q4: Can I use the Kelly result directly as perpetual contract leverage? No. You should first determine acceptable loss and notional position, then look at margin and liquidation price; leverage is an amplification tool, not the Kelly output itself.
Q5: What if the calculated f* is negative? A negative f* means there is no positive expectancy under this set of win rate and payoff ratio, and you should not place a trade; stop trading with those parameters and go back to the strategy and data itself, rather than forcing an answer for "how much can I still open."
Conclusion
The Kelly criterion translates "I think I have an edge" into a calculable position cap reference, but the edge must first be honestly estimated, and estimation error in crypto markets is large. The practical path is usually: record net results → calculate f* → switch to fractional Kelly → convert to notional position using stop-loss → set a separate hard cap for leverage.
To read alongside daily market and liquidity context, see the Crypto Daily Market Report.
Risk warning: This article is for educational and informational purposes only and does not constitute any investment advice. Kelly criterion output ≠ guaranteed profit; incorrect win rate/payoff ratio estimates may lead to severe losses. Crypto asset prices are highly volatile, and leverage and derivatives trading may result in total loss of principal. Please make independent judgments based on your own risk tolerance (DYOR) and consult professional advisors when necessary.
Recommended
View more